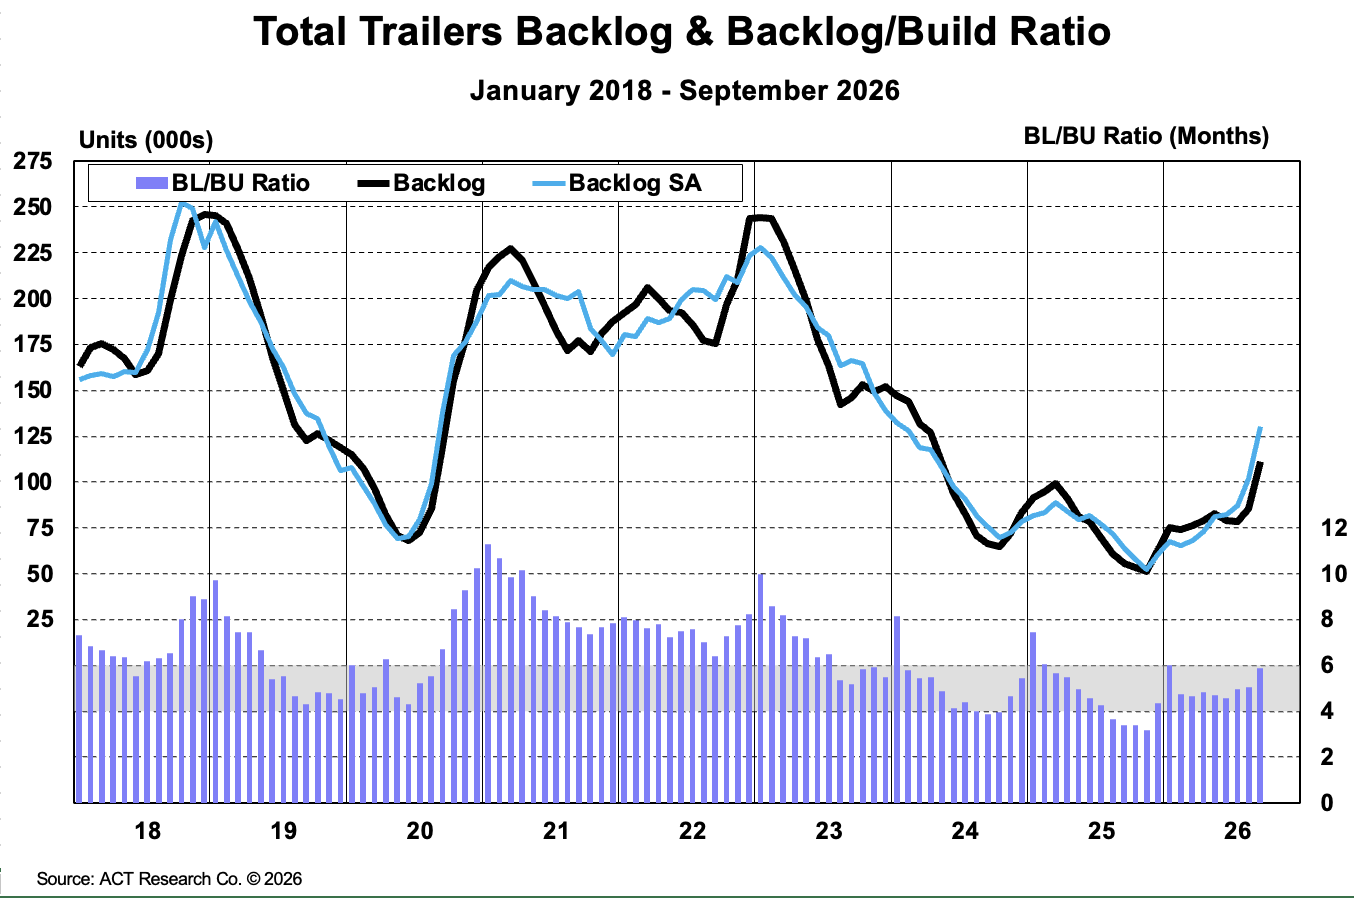
As reported in this month’s issue of ACT Research’s State of the Industry: U.S. Trailers report, net trailer orders in September soared to 42,700 units, marking a dramatic turnaround from the subdued order activity seen a year ago and driving a 29% month-over-month increase in industry backlogs. The backlog-to-build (BL/BU) ratio jumped 90bps m/m to 5.9 months, signaling a notable commitment of production slots well into 2027.
“What a difference a year makes,” said Jennifer McNealy, Director–CV Market Research & Publications at ACT Research. “Last year, the trailer market was in ‘stay afloat’ mode, but today, we’re seeing a perfect storm of order activity. Customers are moving quickly to get ahead of tariff-driven price increases, carriers are enjoying improved profitability, and pent-up replacement demand is being addressed. With a tighter driver supply and supportive freight rates, fleets now have both the willingness and ability to purchase equipment, leading to a strengthening demand environment where backlogs are rising at a pace not seen since the last upcycle.”
State of the Industry: U.S. Trailers Report Overview
ACT Research’s State of the Industry: U.S. Trailers report provides a monthly review of the current US trailer market statistics, as well as trailer OEM build plans and market indicators divided by all major trailer types, including backlogs, build, inventory, new orders, cancellations, net orders, and factory shipments. It is accompanied by a database that gives historical information from 1996 to the present, as well as a ready-to-use graph packet, to allow organizations in the trailer production supply chain, and those following the investment value of trailers, trailer OEMs, and suppliers to better understand the market.
ACT Research Overview
ACT Research is recognized as the leading publisher of commercial vehicle truck, trailer, and bus industry data, market analysis, and forecasts for the North America and China markets. ACT’s analytical services are used by all major North American truck and trailer manufacturers and their suppliers, as well as banking and investment companies. ACT Research is a contributor to the Blue Chip Economic Indicators and a member of the Wall Street Journal Economic Forecast Panel. ACT Research executives have received peer recognition, including election to the Board of Directors of the National Association for Business Economics, appointment as Consulting Economist to the National Private Truck Council, and the Lawrence R. Klein Award for Blue Chip Economic Indicators’ Most Accurate Economic Forecast over a four-year period. ACT Research senior staff members have earned accolades including Chicago Federal Reserve Automotive Outlook Symposium Best Overall Forecast, Wall Street Journal Top Economic Outlook, and USA Today Top 10 Economic Forecasters. More information can be found at www.actresearch.net.
Additional Resources
Preliminary net trailer orders in September were 42,700 units, more than 32,000 units higher than last September’s order intake. While appearing meteoric, it’s important to remember that the 311% y/y gain is against a very easy 2025 comparison. Seasonal adjustment (SA) takes the month’s volume to 36,700 units, the third best seasonally adjusted order volume in the past 55 months. So, while net orders were up 18,000 units, or 75% sequentially on a nominal basis, on a seasonally-adjusted basis, the rise was less than 9%, or about 2,900 units from August’s SA order intake. Final September trailer industry data will be available later this month. This preliminary order estimate is typically within ±5% of the final order tally.
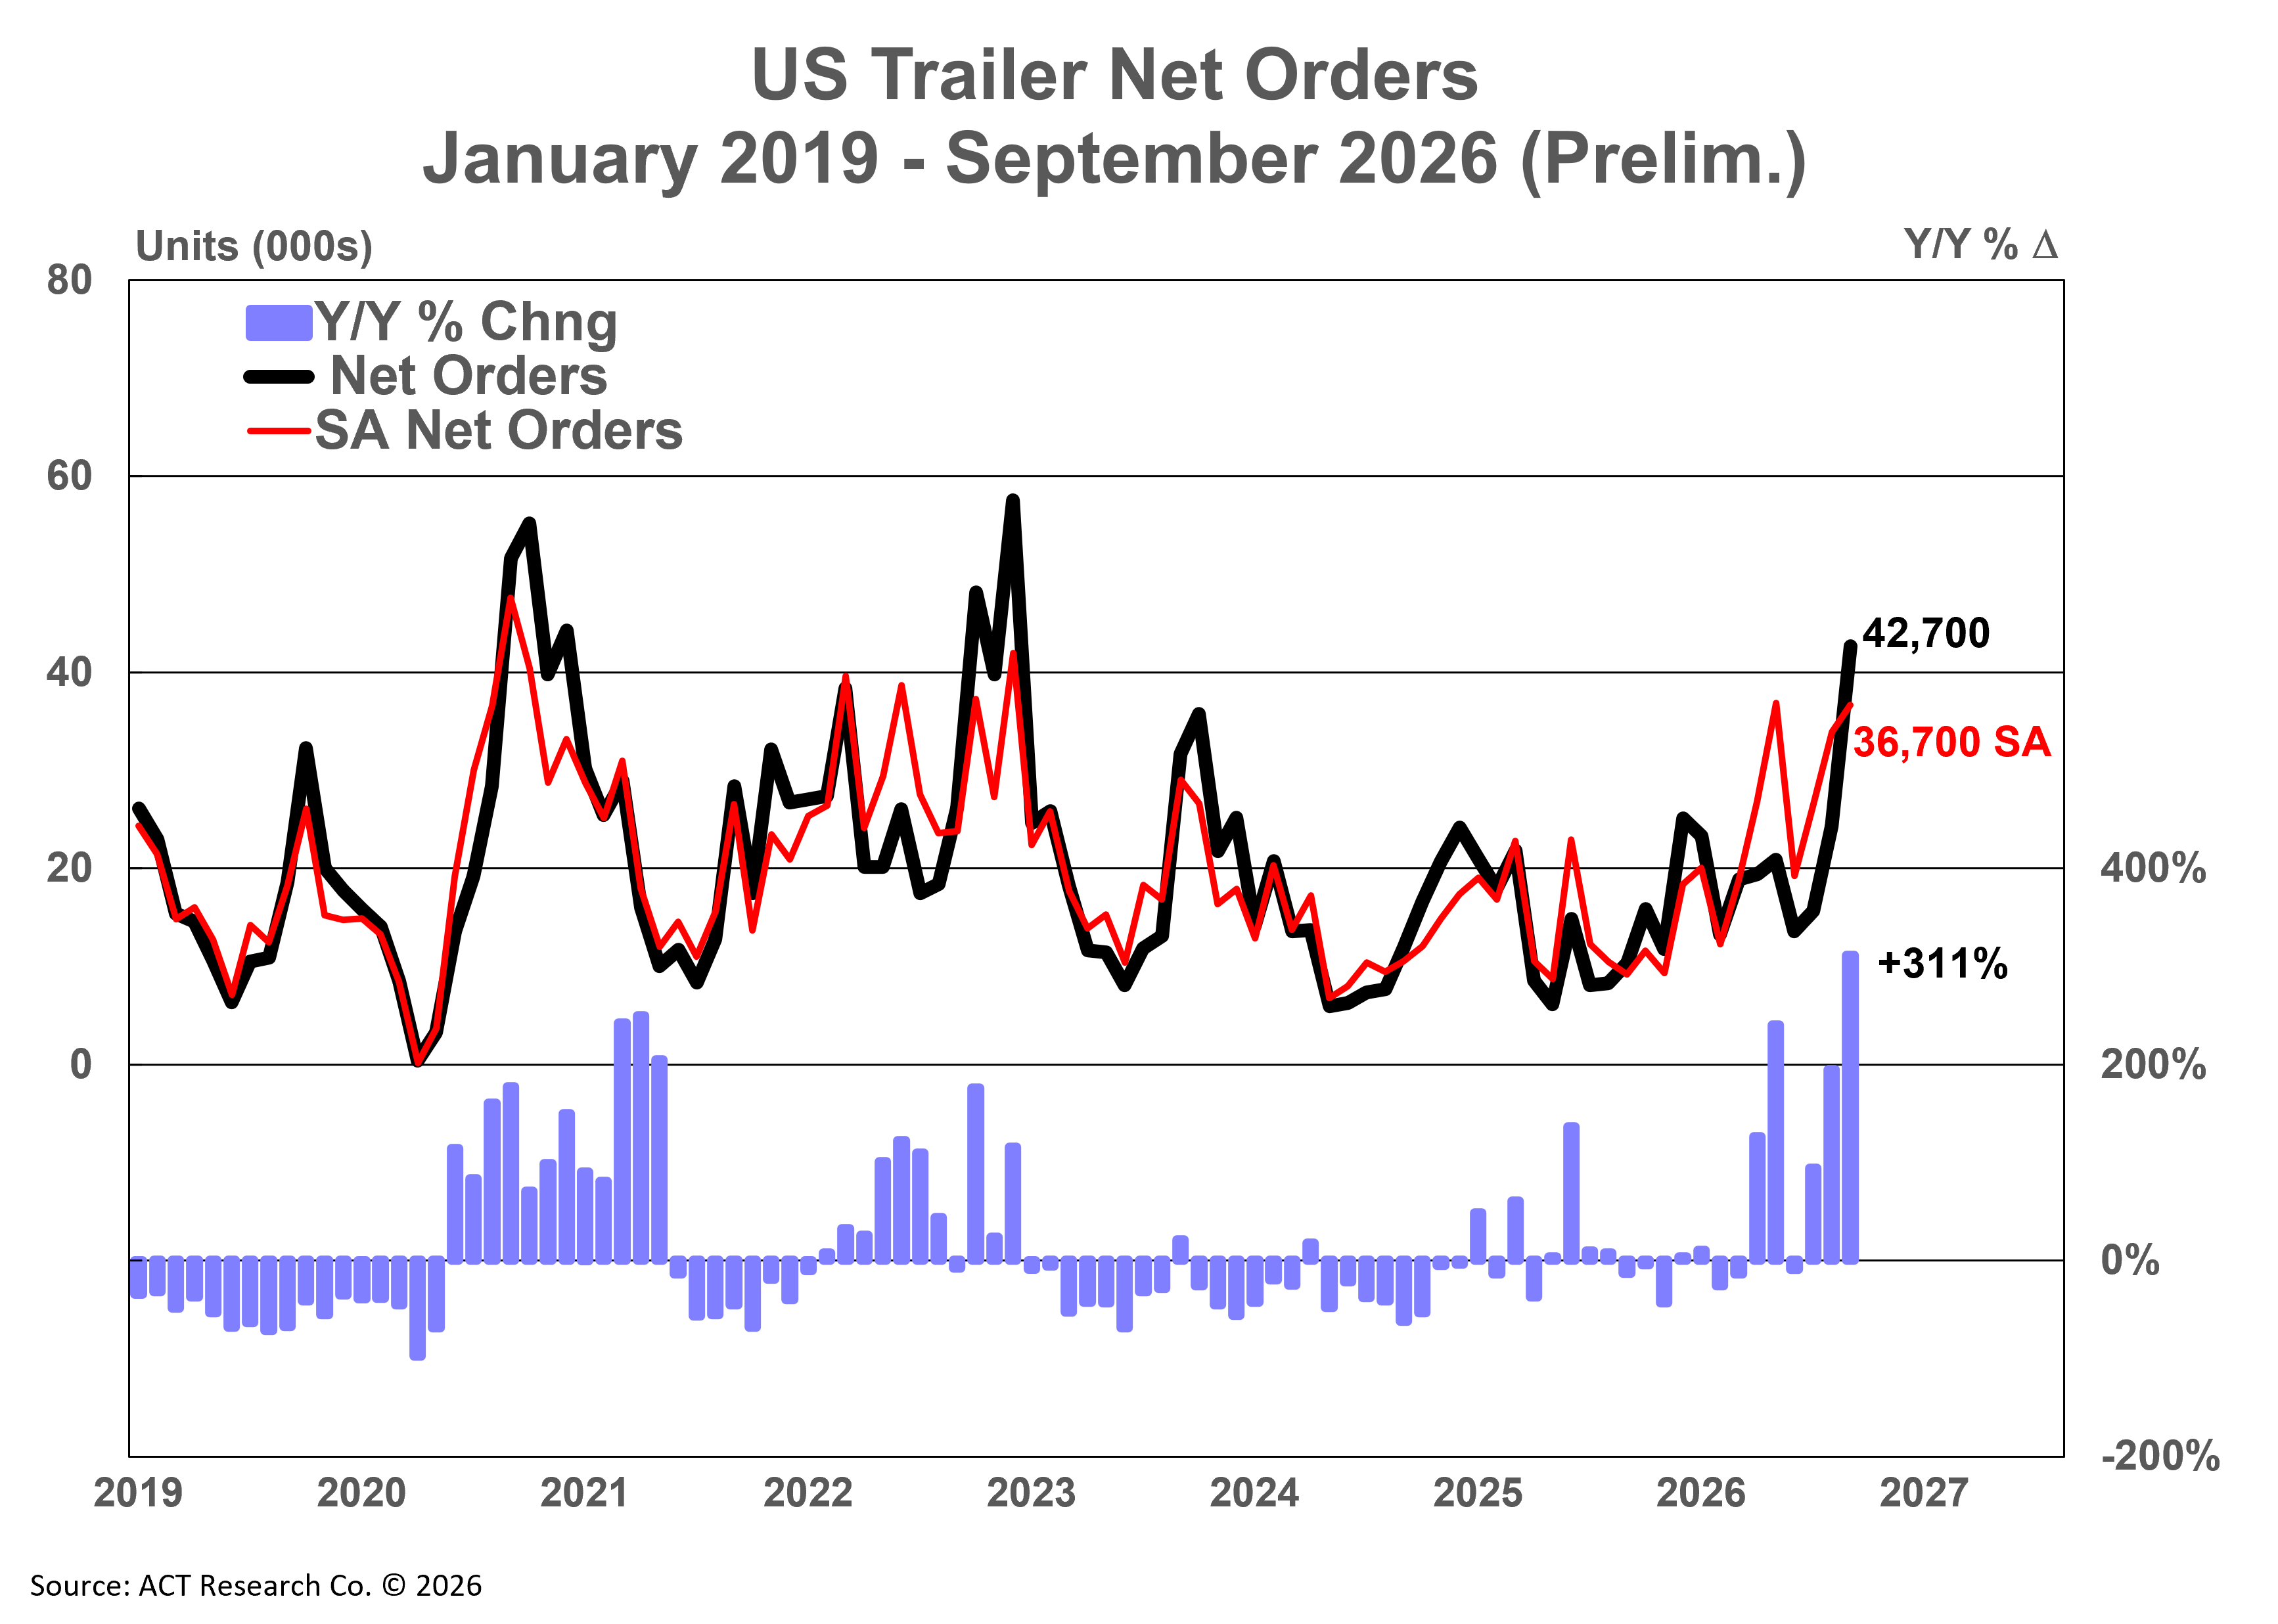
“Seasonally speaking, September net orders should have improved sequentially, so the uptick from August was no surprise” said Jennifer McNealy, Director CV Market Research & Publications at ACT Research. She continued, “The degree of improvement, however, by historical standards was atypical, continuing the unusual pattern of the 2025-2026 order cycle. Orders that should have been placed in September of 2025, for the new cycle, weren’t placed until December/January, and as the season continued so did the gradual uptick in order placement, in general. While comparisons were outsized, in seasonal terms, September’s performance built on seasonally strong orders since May.”
McNealy concluded, “ACT Research continues to hear that the dramatic spike in US trailer orders is a four-fold event: customers ordering ahead of tariff-related price increases, healthier long-term profitability conditions for carriers, pent-up replacement demand, and a sharply tighter driver supply. The current US trailer industry environment is a perfect storm: Carriers now have both the willingness and the ability to purchase equipment, and are inspired to do so sooner rather than later, as they also face rising prices and an untested domestic supply chain that could cause build constraints, lengthier production queues, and delayed deliveries. We often make the case that there is a profitability-related component that makes demand somewhat binary. It would appear that the switch has been flipped. Coming in well above current build levels, industry backlogs are expected to rise by around 18,000 when full industry data are reported.”
- Cancellation Rate as a % of Backlog: 1.0%
- Backlogs: -5% m/m
Click here to learn more information about ACT's Mexican Trailer Market report.
ACT Research is featured regularly by major news outlets for our work covering Class 8 truck orders, sales, forecasting, used truck sales, freight rates, trailer sales, and much more. Get more trends, HERE.
Save time with ACT Research’s media kit. Access ACT Research’s analyst bio, logos, press releases, video library, and more at your convenience. Our analysts are committed to delivering the most accurate data and forecasts. Looking for a speaker? Each analyst is available to speak at your conference or event. Access Media Kit Here.
